Proving Insurance to a Minnesota Officer
Picture this: you're out enjoying a beautiful Minnesota day on your ATV or UTV, cruising along a ditch or hitting a favorite trail, when suddenly, you see those flashing lights in your rearview. Your heart might sink a little, and the first thought that often pops into mind is, "Do I have all my paperwork? Specifically, can I prove I have insurance?" It's a common moment of panic, and understanding exactly what a Minnesota officer needs to see when it comes to your off-highway vehicle's insurance can save you a lot of headache and hassle. This guide is here to walk you through everything you need to know about proving your ATV or UTV insurance to a Minnesota officer, ensuring your next ride is worry-free.
Why Proof of Insurance Matters in Minnesota
Navigating the rules and regulations for ATVs and UTVs in Minnesota can sometimes feel like a maze, but one area that's pretty straightforward, yet often overlooked, is insurance. It's not just a good idea; in many situations, it's a legal requirement that carries real consequences if you don't have it or can't prove it.
The Legal Requirement for ATVs and UTVs
Minnesota's regulations are designed to ensure responsible riding, and that includes financial responsibility. While you might not need insurance for every single scenario, like riding exclusively on your own private land, the moment you venture onto public trails, ditches, or roads (where legally permitted), that's when insurance often becomes non-negotiable. The state wants to make sure that if something goes wrong – an accident, property damage, or an injury to another person – there's a safety net in place to cover the costs. This protection isn't just for others; it's also a significant safeguard for you, the rider, from potentially devastating financial liabilities.
Think about it this way: if you're riding a county road ditch and swerve to avoid a deer, accidentally damaging someone's mailbox, your liability insurance is what steps in to cover the repair costs. Without it, that bill comes directly out of your pocket. The Minnesota DNR and local law enforcement are keenly aware of these risks, which is why they will often ask for proof of insurance during routine stops or after an incident. Understanding [Minnesota Liability Coverage for Riders] is critical to ensuring you meet these requirements.
It's also worth noting that the requirements can sometimes vary depending on where you're riding. A private trail system might have its own insurance stipulations, but generally, if you're interacting with public lands or rights-of-way, assume insurance is required. This also applies to scenarios like riding on ice roads or crossing highways, where the risk of interaction with other vehicles or property increases.
Consequences of Not Carrying Proof
The immediate consequence of not being able to produce valid proof of insurance to a Minnesota officer can range from a warning to a substantial fine. In the eyes of the law, not having your proof on hand is often treated the same as not having insurance at all, at least initially. A conservation officer or sheriff's deputy has the authority to issue a citation, which means a trip to court and a potential financial penalty. These fines can add up quickly, especially when you factor in court costs and potential surcharges.
Beyond the immediate financial hit, there are other, more severe ramifications. If you're involved in an accident and found to be uninsured, the financial burden of damages and injuries falls squarely on you. Imagine a collision with another machine on a busy trail, or a situation where you accidentally injure a pedestrian (unlikely on most ATV trails, but possible on shared-use paths or during road crossings). Without liability coverage, you could be facing medical bills, property damage claims, and even lawsuits that could impact your financial well-being for years.
In some extreme cases, particularly with repeat offenses or severe accidents, an officer might even have grounds to impound your machine until proper insurance can be verified or other legal matters are resolved. While this is less common for a simple "no proof" situation, it underscores the importance of taking this requirement seriously. These penalties aren't meant to be punitive for the sake of it; they're designed to encourage all riders to be prepared for the unexpected and to mitigate risks for everyone enjoying Minnesota's outdoors. It's a key part of staying compliant with rules like those covered in [Fines for Riding Minnesota Unregistered] or [Minnesota Penalties for a Missing Sticker], which often encompass insurance violations too.
What Counts as Valid Proof of Insurance
When that officer asks for your insurance, what exactly are they looking for? It's not just a verbal assurance that you "have insurance." They need to see official documentation that confirms your coverage is active and applies to the machine you're operating. Being prepared with the right type of proof is half the battle.
Acceptable Documentation Formats
Most insurance companies provide a standard insurance identification card, often referred to as an "ID card" or "proof of insurance card." This is typically a small, wallet-sized card that clearly displays your policy number, the effective dates of your coverage (start and end dates), the name of the insured, and a description of the insured vehicle, including its VIN (Vehicle Identification Number). A physical card is always a reliable option, especially if you store it in a waterproof pouch on your machine.
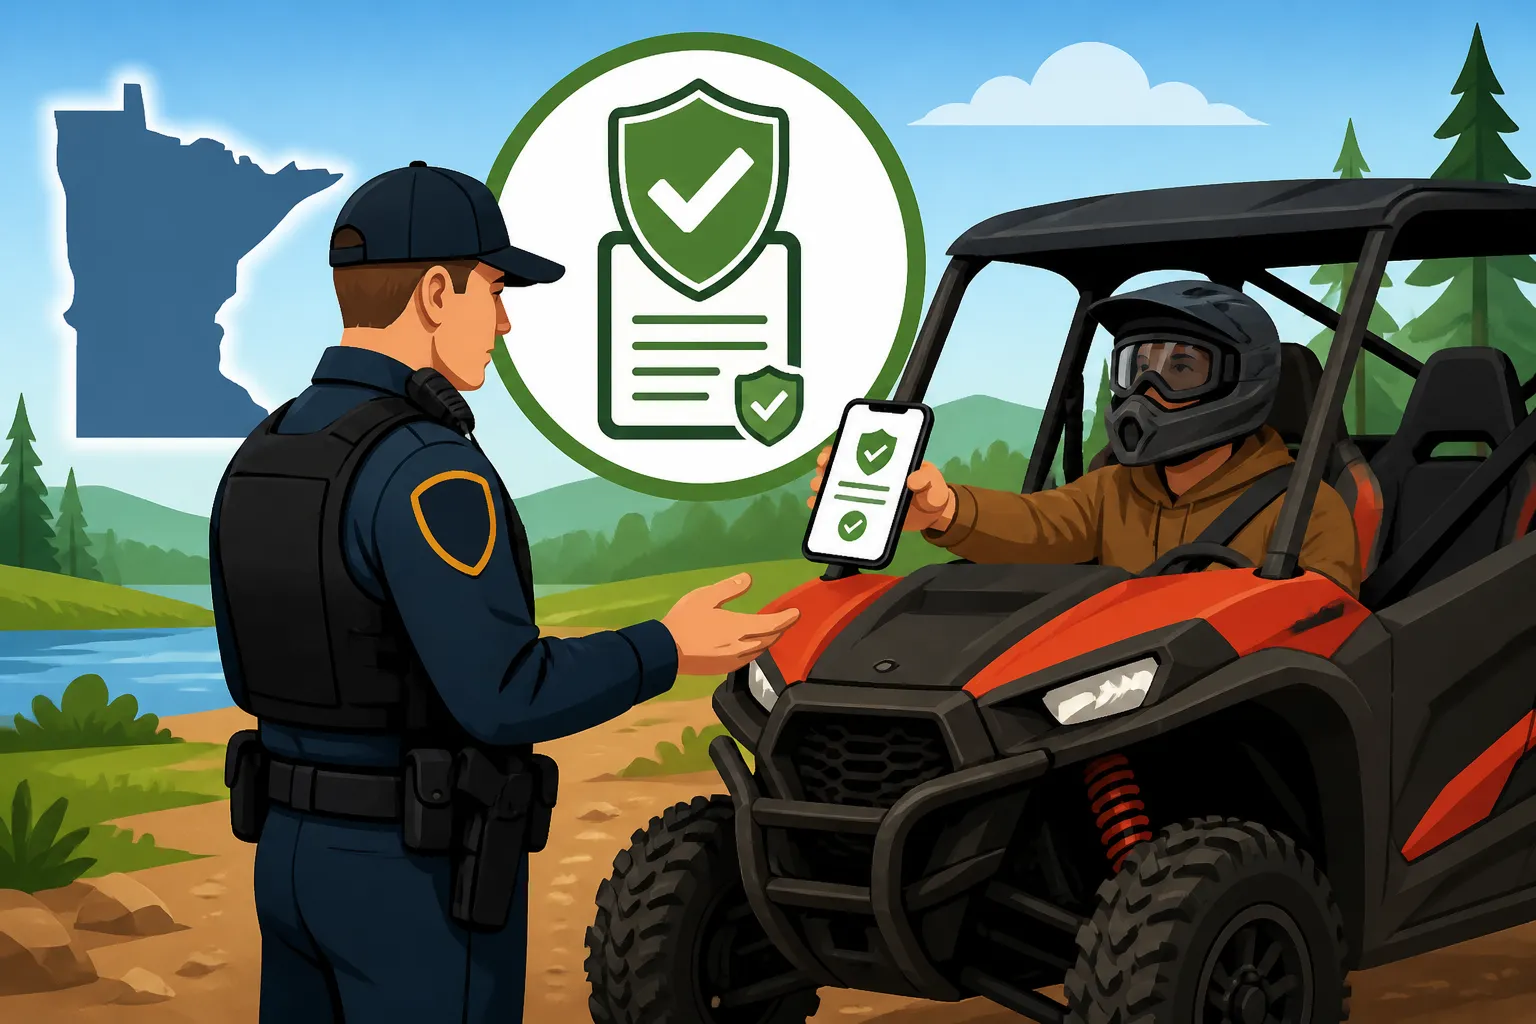
However, in this digital age, many insurers also offer digital proof of insurance. This could be an electronic image of your ID card stored on your smartphone, or access to your policy details through your insurer's mobile app. While digital proof is convenient, it comes with a caveat: your phone needs to be charged, functional, and easily accessible. If your phone dies, or you're in an area with no signal and can't access the app, that digital proof becomes useless. Some riders take a screenshot of their digital card as a backup, which can be a smart move. Regardless of format, the officer will be checking that the dates are current and that the VIN on the card matches the VIN on your ATV or UTV.
An insurance declarations page, which is a more detailed summary of your policy, can also serve as proof, though it's less convenient to carry. This page will list all your coverages, limits, and deductibles, along with the essential policy information. While it's perfectly valid, it's usually too cumbersome for trailside checks. The key is that the document must be legible, current, and clearly link the insurance policy to the specific machine you are operating. For more on what your policy should entail, refer to [Insuring an ATV in Minnesota].
What If You Don't Have an Insurance Card?
It happens to the best of us. Maybe your physical card is lost, forgotten at home, or you just purchased a new policy and haven't received the hard copy yet. In these situations, don't panic immediately, but be prepared for a bit more work. If you have immediate access to your smartphone, try logging into your insurer's app or website. Most major insurance carriers offer digital access to your policy documents, allowing you to pull up the necessary proof on the spot. If you can, take a screenshot of the insurance card or declaration page for easy retrieval, even if cell service is spotty.
If digital access isn't an option, you might need to contact your insurance provider directly. Many insurers have 24/7 customer service lines where they can email or fax proof of insurance to an officer or even directly to your email address. This, of course, relies on the officer's patience and your ability to make a call, which might be tricky in remote areas. For newly purchased policies, many insurers provide a temporary insurance binder or "proof of coverage" document via email immediately after purchase. This temporary document serves the same purpose as a physical card until your official documents arrive.
The bottom line is that while you might still receive a citation for not having immediate proof, quickly providing it to the authorities afterward (often within a specified number of days) can sometimes lead to the ticket being dismissed or reduced. It's crucial to address it promptly and provide the required information as soon as possible. This scenario highlights why it's so important to think about [Do You Carry Papers on a Minnesota Trail?] before you head out.
Special Cases: Rented or Borrowed Machines
Riding a machine that isn't yours adds a layer of complexity to insurance proof. If you're renting an ATV or UTV from an outfitter or dealer, clarify their insurance policy before you hit the trails. Reputable rental companies will have their machines insured, and they should provide you with proof of that coverage, or details on any supplemental insurance you might need or want to purchase for your rental period. Make sure this documentation clearly states that you, as the renter, are covered, and keep it with you.
When borrowing a machine from a friend or family member, it typically falls under the owner's insurance policy. However, this isn't a given and can vary depending on the specific policy terms. It's absolutely crucial to confirm with the owner that their policy extends coverage to anyone operating the machine with their permission. You'll need to carry their proof of insurance, which should clearly identify the machine's VIN. If their policy doesn't cover permissive use, or if you're unsure, it might be wise to explore a non-owner ATV insurance policy or ensure you have your own coverage that might extend to borrowed machines.
Always discuss these details upfront. A quick conversation can prevent a stressful encounter with law enforcement and protect both you and the machine's owner from potential liabilities. It's a good time to remember that your homeowner's policy might not cover your off-highway vehicle, especially away from your property. This is why asking [Does a Homeowners Policy Cover a Quad?] is an important question to address with your insurance agent.
Best Practices for Carrying and Presenting Proof
Having the insurance is one thing; being able to quickly and effectively present it to an officer is another. A little preparation and knowing how to interact can make a big difference in how smoothly your stop goes.
Keeping Your Documents Accessible and Safe
Whether you prefer physical or digital proof, accessibility and protection are key. If you opt for physical cards, invest in a waterproof and tear-resistant document holder or a small, durable pouch. This can be stored in a secure compartment on your ATV or UTV, like a cargo box, or even in a zippered pocket of your riding jacket. Minnesota weather can be unpredictable, and wet, muddy, or torn documents won't be much help to an officer. Make sure the pouch is easily retrievable without having to unstrap a bunch of gear or dig through a packed cooler.
For digital proof on your phone, charge your device fully before a ride, especially if you're heading into areas with limited access to power. Consider keeping a portable power bank with you as a backup. Taking a clear screenshot of your insurance card and saving it to your photos can also be a lifesaver if you lose cell signal and can't access an app or website. Some riders even go so far as to store a laminated copy of their insurance card inside their helmet bag or in a small, secured bin. Products designed for secure storage on ATVs, such as those from SuperATV, can be excellent for keeping these important papers safe from the elements and readily available.
Ultimately, the goal is to have your proof of insurance in a place that's easy to reach, protected from the elements, and clearly legible when requested. This preparation not only demonstrates responsibility but also streamlines any interaction with law enforcement, minimizing delays and potential frustration.
Interacting With a Conservation Officer or Law Enforcement
Being pulled over is rarely a fun experience, but how you handle it can significantly impact the outcome. When an officer signals you to stop, do so safely and promptly. Turn off your engine, remove your helmet (if applicable and safe to do so), and keep your hands visible. A calm, cooperative demeanor goes a long way. When asked for your documents, state clearly that you have them and where they are located before reaching for them. For example, "Officer, my insurance card is in my left jacket pocket, may I retrieve it?"
Hand over your proof of insurance, along with your ATV registration and any necessary safety certificates, without delay. The officer will typically examine the document for validity, checking the dates, VIN, and policyholder information. Avoid arguing or becoming defensive; answer questions honestly and respectfully. If you're riding with a group, ensure everyone knows where their own documents are and is prepared to produce them individually. Remember that conservation officers and other law enforcement personnel are simply doing their job, ensuring everyone on Minnesota's trails and roadways is compliant with the law, as highlighted by [What a Minnesota Conservation Officer Asks For].
This calm and prepared approach not only reflects positively on you but also helps the officer complete their check efficiently. Think of it as a brief, formal interaction where showing respect and preparedness can prevent a minor stop from escalating into a more complicated situation. Remember to keep any alcoholic beverages secured and out of reach, and certainly not open, as that can lead to additional issues related to [Minnesota Alcohol Limits for ATV Operators].
What to Do If You Can't Produce Proof on the Spot
Despite your best efforts, there might be a time when you simply cannot produce proof of insurance immediately. Maybe your phone battery died, your physical card blew away, or you genuinely forgot it. In this scenario, remain calm and explain the situation to the officer. Do not lie or try to bluff your way out of it. Honesty is usually the best policy, even if it results in a citation.
The officer will likely issue you a citation for failure to produce proof of insurance. This is often a "fix-it" ticket, meaning you'll have a set amount of time (e.g., 7-10 days) to present valid proof to the court or the issuing agency, and the charge might be dismissed or the fine reduced. It's crucial to follow the instructions on the citation precisely. Contact your insurance company immediately to obtain a copy of your valid proof of insurance. Then, present it to the designated authority (often the clerk of court or a specific law enforcement office) as soon as possible.
Failure to follow up can result in more serious penalties, including higher fines, additional charges, or even a warrant for your arrest if you simply ignore the ticket. Even if you believe you have a valid reason for not having the document, the responsibility lies with you to present the proof to the proper channels within the given timeframe. It's far easier to deal with the minor inconvenience of producing the document later than to face the escalating consequences of ignoring a citation.
Understanding Your Minnesota ATV Insurance Policy
Having a policy is great, but truly understanding its components ensures you're adequately covered and ready for anything. It’s not just about having a piece of paper; it’s about having the right coverage for your riding style and location.
Key Coverage Types for Minnesota Riders
When you acquire ATV or UTV insurance in Minnesota, you'll typically encounter several types of coverage, each designed to protect you in different scenarios. The most fundamental and often legally required coverage is Liability Insurance. This is what pays for damages and injuries you might cause to other people or their property while operating your machine. If you accidentally hit another rider, damage a park bench, or cause an injury, your liability coverage kicks in. This is the coverage that officers are primarily concerned with when asking for proof.
Beyond liability, many riders opt for additional protections. Collision Coverage pays for damage to your own ATV or UTV if it collides with another vehicle, an object (like a tree), or if it rolls over. Comprehensive Coverage protects against non-collision incidents such as theft, vandalism, fire, or damage from natural disasters. If your machine is stolen from your garage or vandalized on a trail, comprehensive coverage would help cover the repair or replacement cost.
Uninsured/Underinsured Motorist (UM/UIM) Coverage is also very important. This protects you if you're involved in an accident with another rider who either doesn't have insurance or doesn't have enough insurance to cover your damages and medical bills. Given that not everyone on the trail might be as diligent with their insurance as you are, UM/UIM can be a lifesaver. Finally, many policies offer Medical Payments (MedPay) which covers medical expenses for you and your passengers, regardless of who was at fault in an accident. Understanding these coverages helps you tailor your policy to your specific needs and riding habits, providing peace of mind whether you're riding [Minnesota's Ditch Riding Rules] or a dedicated trail.
How Your Policy Details Affect Proof
The devil is often in the details when it comes to insurance. When presenting proof to a Minnesota officer, they will be meticulously checking a few key pieces of information to ensure the document is valid and relevant to your current situation. First and foremost, they'll verify that the VIN (Vehicle Identification Number) listed on your insurance card or document precisely matches the VIN on your actual ATV or UTV. A mismatch here can cause significant delays and questions, as it might indicate the insurance is for a different machine or that the document is incorrect.
Next, the Effective Dates of your policy are crucial. The officer needs to see that your coverage is active and hasn't expired. An expired card, even if you've renewed your policy, is not valid proof. It's always a good idea to update your physical or digital card as soon as you receive renewal documents. They will also look for the Name of the Insured to ensure the policy belongs to someone authorized to operate or insure the machine. If you're borrowing a machine, the owner's name would typically be on the policy, with an implication (or explicit statement) that permissive users are covered.
Finally, they might quickly glance at the Type of Coverage listed, particularly looking for liability coverage, which is the most common legal requirement for public use. While they aren't insurance experts, they'll want to see that the basic legal requirements are met. It's why taking the time to understand your policy fully and regularly reviewing documents is so important. Knowing [Minnesota ATV Insurance Cost] can also help you understand the value and necessity of comprehensive coverage versus basic liability.
| Feature | Physical Insurance Card | Digital Insurance Card (on Phone) |
|---|---|---|
| Pros | Always accessible (if carried), no battery needed, tangible. | Convenient, easily updated, no risk of physical loss/damage. |
| Cons | Can be lost, damaged by weather, outdated. | Requires charged phone, cell service, screen visibility. |
| Officer Preference | Generally accepted without issue. | Accepted, but may require officer to handle your device. |
| Best Practice | Laminated or in waterproof pouch, updated regularly. | Screenshot backup, full battery, screen protector for visibility. |
| Durability | Depends on material and storage. | Dependent on device durability and battery life. |
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.